Company profile · ISRG
Intuitive Surgical, Inc.
Robotic surgery platforms and their consumables
Exceptional Company Series · No. 1
Passes all five structural tests and clears our elevated bar on both the strength of the business today and the consistency of its earnings record. An assessment of business quality, not a buy signal — exceptional can also be expensive. Why → · About the series →
Listen instead
3:52 · 3.7 MB · narrated by a synthetic voice, not by the author Also on Spotify →
Read the transcript
This is The Conviction Play. Intuitive Surgical, surgical robotics. Number 1 in our Exceptional Company Series, the businesses our framework grades exceptional.
Intuitive makes the da Vinci surgical robot, the system a surgeon drives from a console nearby, working through incisions a few millimetres wide instead of opening the patient up. But the robot is the shop window, not the shop. Every operation its 11,710 installed machines perform consumes single-use instruments and service, so 84% of revenue is recurring and scales with surgery itself, not with machine sales. The people are the lock-in: surgeons train for years on the console and build careers on it. Earnings have compounded at 17.7% for twelve years, rising in five of every six comparisons, debt-free. That is what we mean by a structural compounder.
The maker of the da Vinci robotic-surgery platform and the Ion lung-biopsy system, the tools of minimally invasive medicine: smaller incisions, steadier instruments, faster recoveries.
Why the economics are exceptional. A da Vinci system is a seven-figure capital sale, but it is the beginning of the customer relationship, not the end. Every procedure the installed base performs consumes instruments engineered for a limited number of uses, plus service on every machine.
The switching cost is institutional. The surgeon sits at its centre, hundreds of hours to proficiency, and many now meet the platform in residency, learning robotic surgery as da Vinci surgery. But around them sit credentialing, operating-room workflow, biomedical engineering familiarity, service infrastructure, procedure-specific instrument sets and years of procurement history. A rival is not competing with a machine; it is competing with everything a hospital has built around one.
The moat is made of evidence. Regulators clear robotic surgery procedure by procedure, on decades of published outcomes across millions of operations. A well-funded challenger can build a capable robot in five years; it cannot build twenty years of clinical evidence in five years.
The honest risk. Medtronic's Hugo and J and J's Ottava do not need to beat da Vinci to hurt Intuitive, and Ottava received FDA marketing authorisation in July 2026, so the competition is no longer theoretical. The damage requires no share loss at all: only that a hospital decides to get three quotes instead of one. Robotic superiority over conventional laparoscopy also remains contested in several high-volume procedures, which means the evidence moat protects incumbency better than it protects pricing.
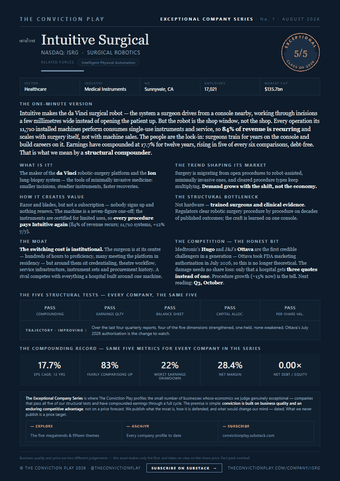
Three numbers to take away. Over 12 years, earnings per share compounded at 17.7% a year. 83% of the year-on-year comparisons were up. The worst fall in earnings was 22%.
The full profile of Intuitive Surgical, with the charts and the sources, is at the conviction play dot com.
A note before we finish. This episode is narrated by a synthetic voice, not by the author. This is an assessment of business quality. It is not a valuation, not a price target, and not a recommendation to buy or sell anything. A company can be exceptional and still be expensive. The Conviction Play publishes general commentary for information only. It is not investment advice and it is not a personal recommendation. Capital is at risk, and the value of investments can fall as well as rise. This assessment reflects what was known on the date of recording, and nothing in it updates itself.
The one-minute version
Intuitive makes the da Vinci surgical robot — the system a surgeon drives from a console nearby, working through incisions a few millimetres wide instead of opening the patient up. But the robot is the shop window, not the shop. Every operation its 11,710 installed machines perform consumes single-use instruments and service, so 84% of revenue is recurring and scales with surgery itself, not with machine sales. The people are the lock-in: surgeons train for years on the console and build careers on it. Earnings have compounded at 17.7% for twelve years, rising in five of every six comparisons, debt-free. That is what we mean by a structural compounder.
The five structural tests
Trajectory: improving ↑ — Over the last four quarterly reports, four of the five dimensions strengthened, one held, none weakened. Ottava's July 2026 authorisation is the change to watch.
The compounding record
The same five measures for every company in the series, so any two can be read against each other.
Why the economics are exceptional
The instrument is the shop window, not the shop. A da Vinci system is a seven-figure capital sale, but it is the beginning of the customer relationship, not the end. Every procedure the installed base performs consumes instruments engineered for a limited number of uses, plus service on every machine.
The switching cost is institutional. The surgeon sits at its centre — hundreds of hours to proficiency, and many now meet the platform in residency, learning robotic surgery as da Vinci surgery. But around them sit credentialing, operating-room workflow, biomedical engineering familiarity, service infrastructure, procedure-specific instrument sets and years of procurement history. A rival is not competing with a machine; it is competing with everything a hospital has built around one.
The moat is made of evidence. Regulators clear robotic surgery procedure by procedure, on decades of published outcomes across millions of operations. A well-funded challenger can build a capable robot in five years; it cannot build twenty years of clinical evidence in five years.
The honest risk. Medtronic's Hugo and J&J's Ottava do not need to beat da Vinci to hurt Intuitive — and Ottava received FDA marketing authorisation in July 2026, so the competition is no longer theoretical. The damage requires no share loss at all: only that a hospital decides to get three quotes instead of one. Robotic superiority over conventional laparoscopy also remains contested in several high-volume procedures, which means the evidence moat protects incumbency better than it protects pricing.
Earnings, twelve years
The deepest fall is 2020, the year surgery itself stopped — and 2022 came close. Neither lasted. The shape is the grade. Source: Legend, from company filings and market data, as at 25 August 2026.
Exceptional Company Series
Intuitive Surgical, Inc. — the two-page fact sheet
Everything on this page, laid out to be read in one sitting or printed: what the business is, the five structural tests, twelve years of earnings, and the honest risk list. No valuation and no price target — the same rule as the writing.
Download the PDF ↓Closing price, USD — not a valuation, not real-time. As of 2026-09-08.
Published 2026-08-24: Sells the da Vinci surgical robot, then earns again on every operation it performs. The piece asks what makes that annuity durable.
- Sector
- Healthcare
- Industry
- Medical Instruments & Supplies
- Head office
- United States
- Employees
- 17,021
- Market cap (as of 2026-09-08)
- USD 131,380,568,064
- Return on equity (as of 2026-09-08)
- +17.4%
- P/E (trailing)
- 42.0×
- Profit margin
- 28.4%
- Beta (5y monthly, vs S&P 500)
- 1.47
- 52-week range
- 328.57 – 603.88 USD
- Website
- intuitive.com
- Growth (YoY, market data)
- Revenue +18.5% · EPS +26.5%
Where this sits
Every company here is put through the same five structural tests. A small number clear all five and stay clear — those are the Exceptional Company Series. The rest are on the same map, each saying in its own words what it passed and what it did not.
New pieces go out by email — and by ear
One company at a time, put through the same five structural tests. No trading alerts, no model portfolio, no urgency — in your inbox or your podcast feed.